Bitcoin Market Post-ETF: Structural Changes and Redefining Market Interpretation (Part 1)
Apr 03 2026
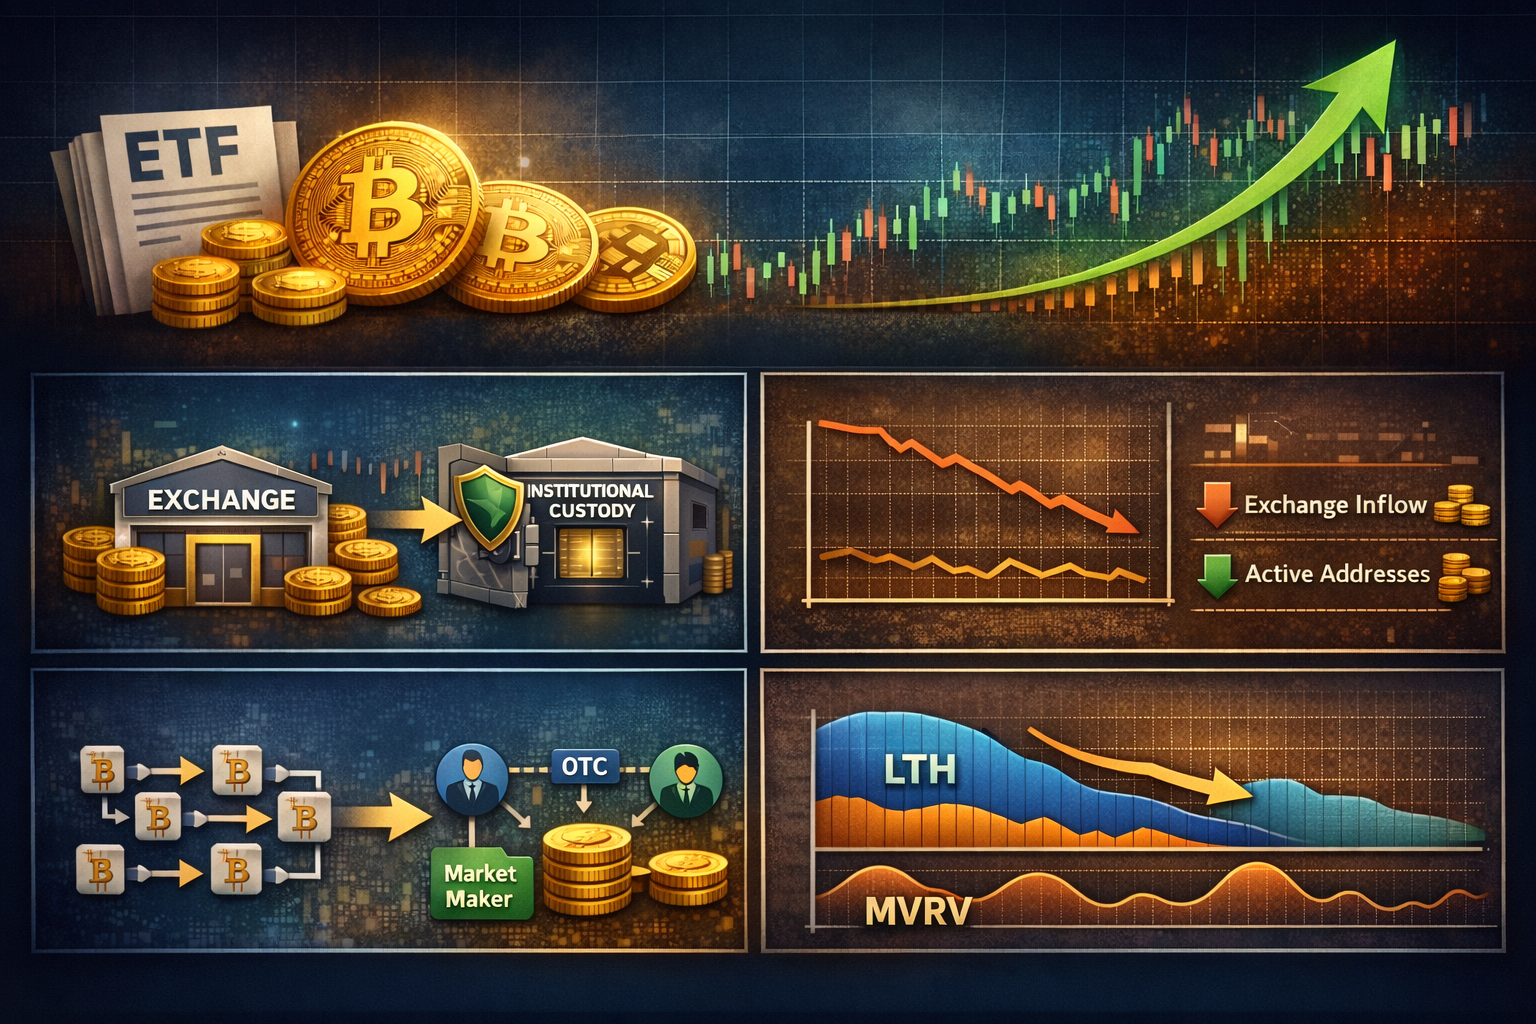
1. Changes in On-chain Data Since the approval of the Bitcoin spot ETF on January 10, 2024, the market structure has shown fundamentally different patterns compared to previous cycles. These changes are clearly visible across various on-chain metrics.
1.1 Shift from Exchange-centric to Custody-centric Structure In past cycles, investors primarily stored and traded assets through exchanges. However, since the ETF approval, institutional investors have been investing indirectly via ETFs rather than holding Bitcoin directly. These assets are stored in institutional-grade custody environments rather than on exchange platforms. Consequently, the primary storage and movement path of Bitcoin has shifted from exchanges to institutional custody, structurally altering the transaction flows observed on-chain.
1.2 Market Expansion and On-chain Activity Decoupling The Bitcoin market has expanded rapidly following the ETF approval, with a continuous increase in institutional capital inflow. Despite this expansion, on-chain activity indicators—such as Exchange Inflow and Active Addresses—have actually decreased or stagnated. While it may appear that transaction volume has dropped, it reflects a shift where individual trades are handled through intermediaries (ETFs, OTC, Market Makers). Instead of every trade being recorded on-chain, they are aggregated, and only the minimum necessary settlement is reflected as on-chain transactions.
1.3 Structural Changes in Cycle Data These shifts affect key on-chain indicators used for cycle analysis, particularly the movement between Long-Term Holders (LTH) and Short-Term Holders (STH). In previous cycles, LTH supply would rapidly decrease during price surges as it was absorbed by new capital, leading to a sharp drop in the LTH/STH ratio. Post-ETF, however, the decline in LTH holdings is more gradual, and the transition to STH is occurring incrementally. This suggests that assets are being maintained long-term within custody environments. As a result, indicators like MVRV are showing smoother, more gradual movements rather than the abrupt overheating signals seen in the past.
2. Changes in Technical Analysis Data The structural shift is also influencing price formation. Clear signs of "overheating" that were consistently observed in past cycles are not as prominent now.
2.1 Pi Cycle Model The Pi Cycle Model identifies market peaks through the crossover of the 111-day MA and 2x350-day MA. Previously, sharp price spikes caused the short-term MA to cross above the long-term MA at market tops. In the current cycle, even with price corrections, this clear crossover hasn't occurred. This suggests that while there were periods of growth, the pace was more gradual than in the past, failing to trigger the typical peak signal.
2.2 200W MA Heatmap The 200-week Moving Average Heatmap gauges market overheating based on price deviation from the long-term average. Past peaks were marked by strong "red zones" (overheating). Currently, while the market saw a rise, these intense red zones did not fully form, and the duration of any overheating was relatively short compared to previous cycles.
To be continued in Part 2.